Idc: Worldwide PC Shipments in Q3 Fell 20 Percent from Last Year
"With macro conditions worsening, the risk is that the outlook for the next few quarters gets worse before it gets better." Stakeholders assess operational and strategic impacts following recent developments.
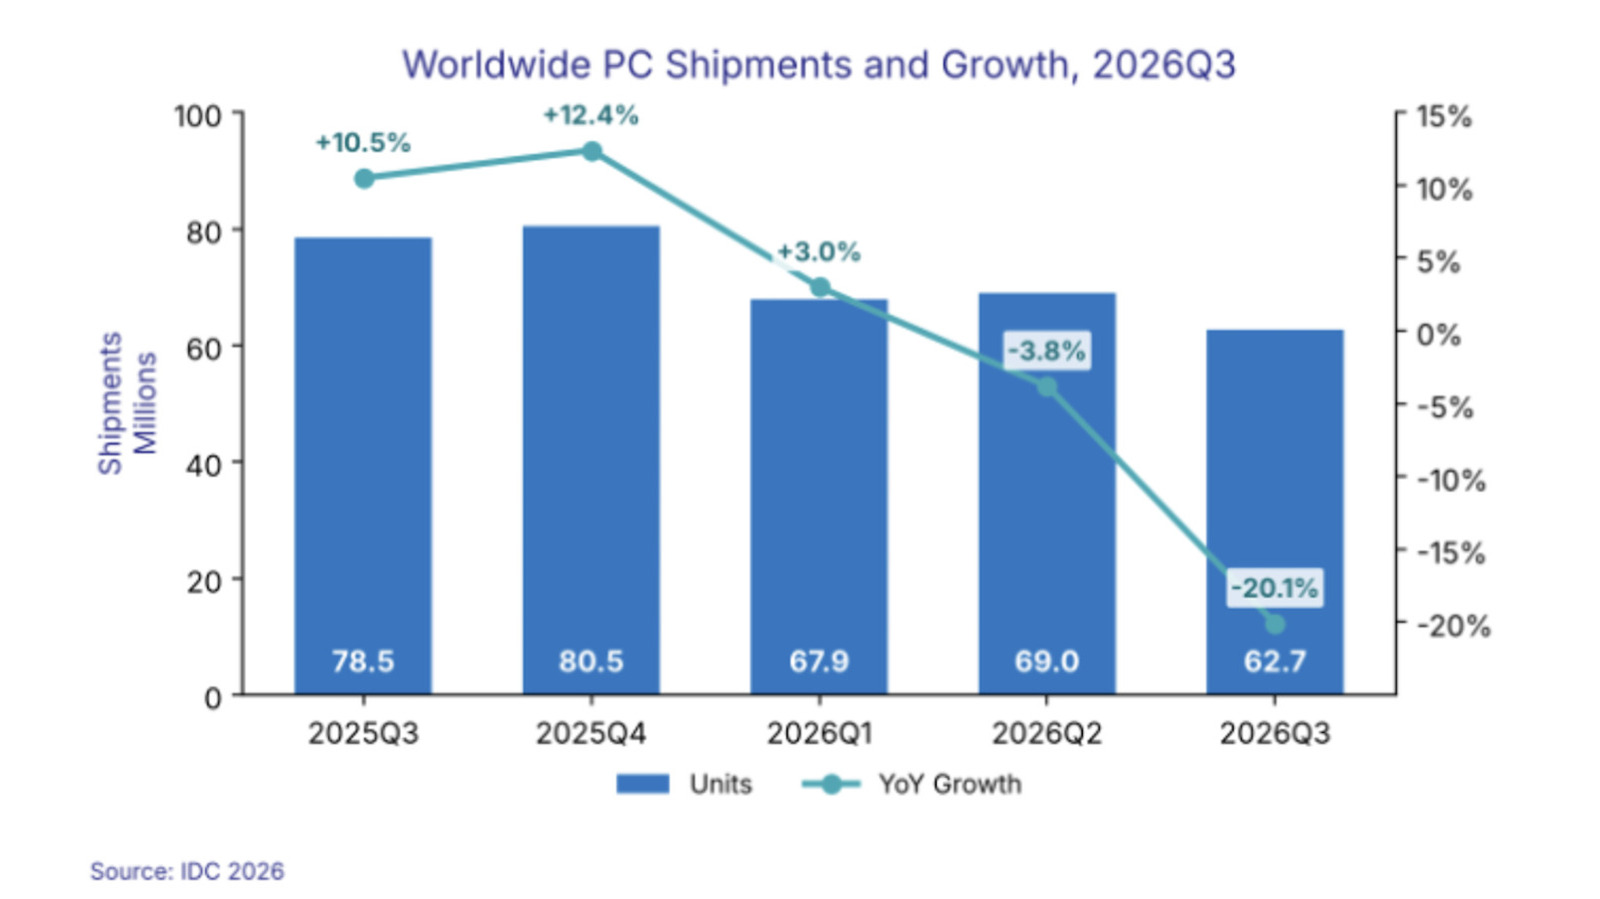
The ongoing evolution of the Technology environment marked another decisive turn today. "With macro conditions worsening, the risk is that the outlook for the next few quarters gets worse before it gets better." According to latest observations, participants are closely evaluating both immediate and forward-looking repercussions.
Executive Key Takeaways
- Primary Signal: "With macro conditions worsening, the risk is that the outlook for the next few quarters gets worse before it gets better."
- Contextual Driver: Stakeholders assess operational and strategic impacts following recent developments.
- Strategic Outlook: Market and policy watchers anticipate critical regulatory and macroeconomic responses.
"With macro conditions worsening, the risk is that the outlook for the next few quarters gets worse before it gets better."
Market & Strategic Implications
Beyond immediate headlines, market participants are weighing secondary effects. The intersection of capital allocations, regulatory scrutiny, and shifting macroeconomic postures continues to elevate risk sensitivity across comparable assets and jurisdictions.
As further clarity emerges in upcoming briefings, institutional observers emphasize unit economics, policy enforcement, and counterparty exposure as primary barometers for long-term trajectory.
Comments (0)
No comments yet. Be the first to share your thoughts!
Leave a Comment