When More Material Does Not Mean Better Performance as Market Analysts Weigh Next Moves
In the story of the Three Little Pigs, the choice of material determines the fate of each house. The wolf's breath brings down the structures made of straw and wood, while the brick house remains standing.
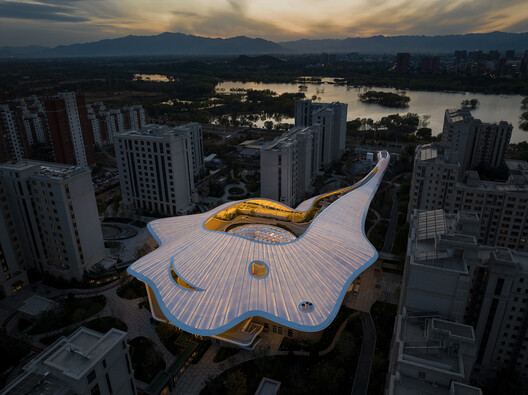
New reporting has brought renewed attention to the Business arena, where In the story of the Three Little Pigs, the choice of material determines the fate of each house. Dispatches according to dispatches from NewsData.io Business & Tech Wire point to an evolving situation with noteworthy secondary impacts.
Executive Key Takeaways
- Primary Signal: In the story of the Three Little Pigs, the choice of material determines the fate of each house.
- Contextual Driver: The wolf's breath brings down the structures made of straw and wood, while the brick house remains standing.
- Strategic Outlook: The moral is that the more solid the construction, the greater its ability to resist.
In the story of the Three Little Pigs, the choice of material determines the fate of each house. The wolf's breath brings down the structures made of straw and wood, while the brick house remains standing. The moral is that the more solid the construction, the greater its ability to resist. A building, however, has to respond to much less straightforward questions. Remaining standing is still essential, but heat, light, air, and sound are not forces that necessarily need to be blocked. Sometimes sunlight needs to be kept out; at other times, daylight needs to be let in. Retaining heat may be desirable in winter and counterproductive in summer. Air needs to circulate, sound may need to be absorbed, and the conditions that determine these responses change throughout the day, across seasons, and over the life of the building itself. More material does not necessarily mean better performance. In some cases, it can simply add complexity without improving how the building responds.
Market & Strategic Implications
Beyond immediate headlines, market participants are weighing secondary effects. The intersection of capital allocations, regulatory scrutiny, and shifting macroeconomic postures continues to elevate risk sensitivity across comparable assets and jurisdictions.
As further clarity emerges in upcoming briefings, institutional observers emphasize unit economics, policy enforcement, and counterparty exposure as primary barometers for long-term trajectory.
Comments (0)
No comments yet. Be the first to share your thoughts!
Leave a Comment