Mapping US Chip Supply Chain: China Accounts for Far More Than It Appears, Report Says
China accounts for about 5 per cent of the equipment and materials directly supplied to the US chip industry when measured by country of manufacture, but its grip on certain rare earths needed for chipmaking is over 90 per cent, according to the Semi...
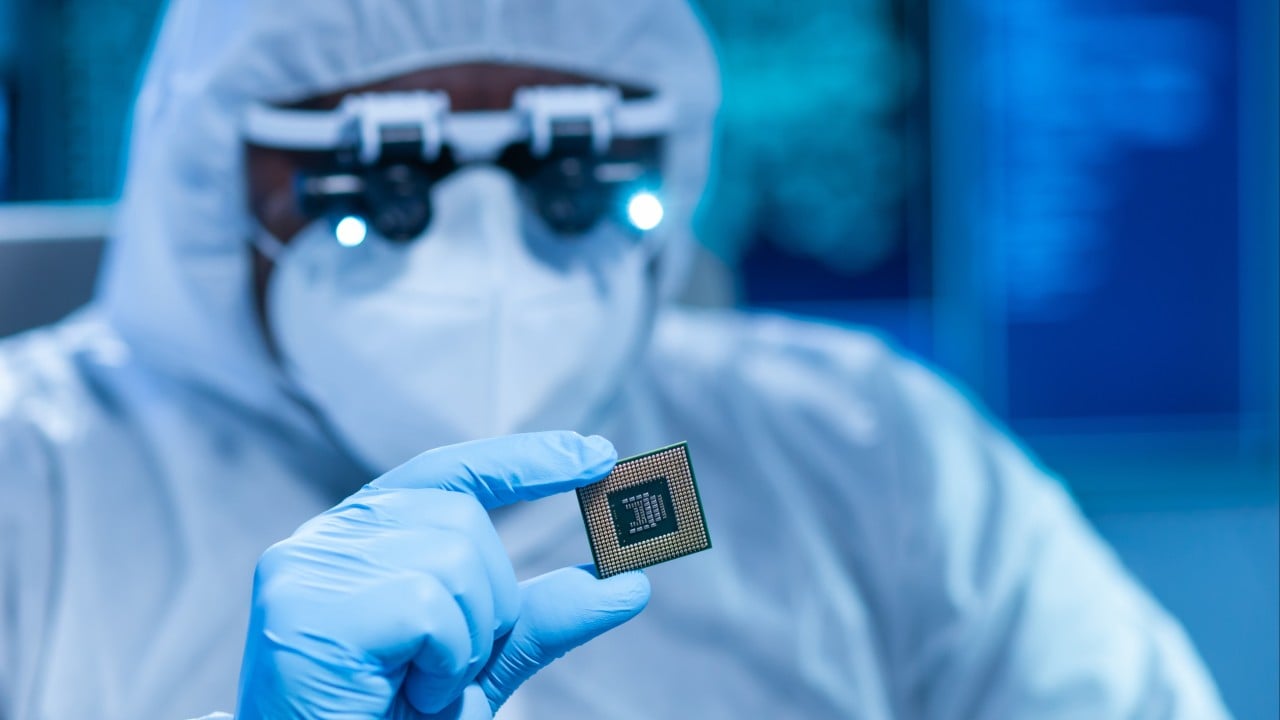
New reporting has brought renewed attention to the World arena, where China accounts for about 5 per cent of the equipment and materials directly supplied to the US chip industry when measured by country of manufacture, but its grip on certain rare earths needed for chipmaking is over 90 per cent, according to the Semiconductor Industry Association (SIA). Dispatches according to dispatches from South China Morning Post (Asia) point to an evolving situation with noteworthy secondary impacts.
Executive Key Takeaways
- Primary Signal: China accounts for about 5 per cent of the equipment and materials directly supplied to the US chip industry when measured by country of manufacture, but its grip on certain rare earths needed for chipmaking is over 90 per cent, according to the Semiconductor Industry Association (SIA).
- Contextual Driver: While 95 per cent of the nearly US$27 billion annual spending by American chipmakers on manufacturing equipment and materials was sourced from companies headquartered in the US, Europe, and Japan, that figure...
- Strategic Outlook: Market and policy watchers anticipate critical regulatory and macroeconomic responses.
China accounts for about 5 per cent of the equipment and materials directly supplied to the US chip industry when measured by country of manufacture, but its grip on certain rare earths needed for chipmaking is over 90 per cent, according to the Semiconductor Industry Association (SIA). While 95 per cent of the nearly US$27 billion annual spending by American chipmakers on manufacturing equipment and materials was sourced from companies headquartered in the US, Europe, and Japan, that figure...
Market & Strategic Implications
Beyond immediate headlines, market participants are weighing secondary effects. The intersection of capital allocations, regulatory scrutiny, and shifting macroeconomic postures continues to elevate risk sensitivity across comparable assets and jurisdictions.
As further clarity emerges in upcoming briefings, institutional observers emphasize unit economics, policy enforcement, and counterparty exposure as primary barometers for long-term trajectory.
Jaison M K is the Founder and Senior Tech Analyst at Incisor News. With an extensive background in digital media architecture, cloud computing, and semiconductor supply chains, he oversees editorial standards and directs technical reporting on sovereign silicon, artificial intelligence infrastructure, and the digital economy. Direct inquiries: jaison@incisornews.tech

Comments (0)
No comments yet. Be the first to share your thoughts!
Leave a Comment