Gen Z Overtakes Older Collectors As Art Market Spending Rebounds Globally: Report
Gen Z high-net-worth collectors have overtaken older generations as the art market’s biggest spenders, with average fine art expenditure more than twice that of older collectors, helping drive a global sales rebound to nearly US$60 billion, according...
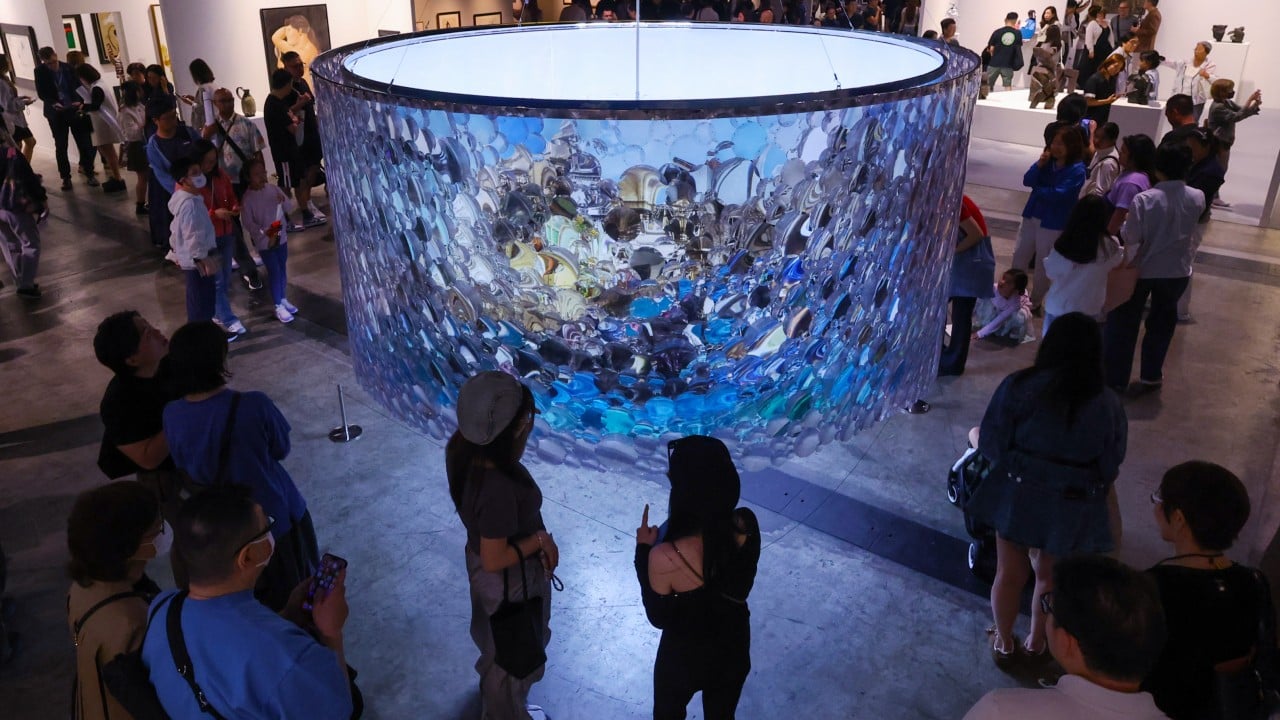
New reporting has brought renewed attention to the World arena, where Gen Z high-net-worth collectors have overtaken older generations as the art market’s biggest spenders, with average fine art expenditure more than twice that of older collectors, helping drive a global sales rebound to nearly US$60 billion, according to the latest Art Basel and UBS market insights. Dispatches according to dispatches from South China Morning Post (Asia) point to an evolving situation with noteworthy secondary impacts.
Executive Key Takeaways
- Primary Signal: Gen Z high-net-worth collectors have overtaken older generations as the art market’s biggest spenders, with average fine art expenditure more than twice that of older collectors, helping drive a global sales rebound to nearly US$60 billion, according to the latest Art Basel and UBS market insights.
- Contextual Driver: The surge came as mainland China and Hong Kong continued to play pivotal roles in the global art market’s growth, according to the Art Basel and UBS Survey of Global Collecting 2026, released earlier...
- Strategic Outlook: Market and policy watchers anticipate critical regulatory and macroeconomic responses.
Gen Z high-net-worth collectors have overtaken older generations as the art market’s biggest spenders, with average fine art expenditure more than twice that of older collectors, helping drive a global sales rebound to nearly US$60 billion, according to the latest Art Basel and UBS market insights. The surge came as mainland China and Hong Kong continued to play pivotal roles in the global art market’s growth, according to the Art Basel and UBS Survey of Global Collecting 2026, released earlier...
Market & Strategic Implications
Beyond immediate headlines, market participants are weighing secondary effects. The intersection of capital allocations, regulatory scrutiny, and shifting macroeconomic postures continues to elevate risk sensitivity across comparable assets and jurisdictions.
As further clarity emerges in upcoming briefings, institutional observers emphasize unit economics, policy enforcement, and counterparty exposure as primary barometers for long-term trajectory.
Comments (0)
No comments yet. Be the first to share your thoughts!
Leave a Comment