Why Morgan Stanley Sees More Upside in Hong Kong Offices Than New York Towers
Higher interest rates have weighed on property markets in both Hong Kong and New York, but Morgan Stanley sees greater upside potential in the Asian financial hub – particularly the office segment – in the months ahead, according to its latest report...
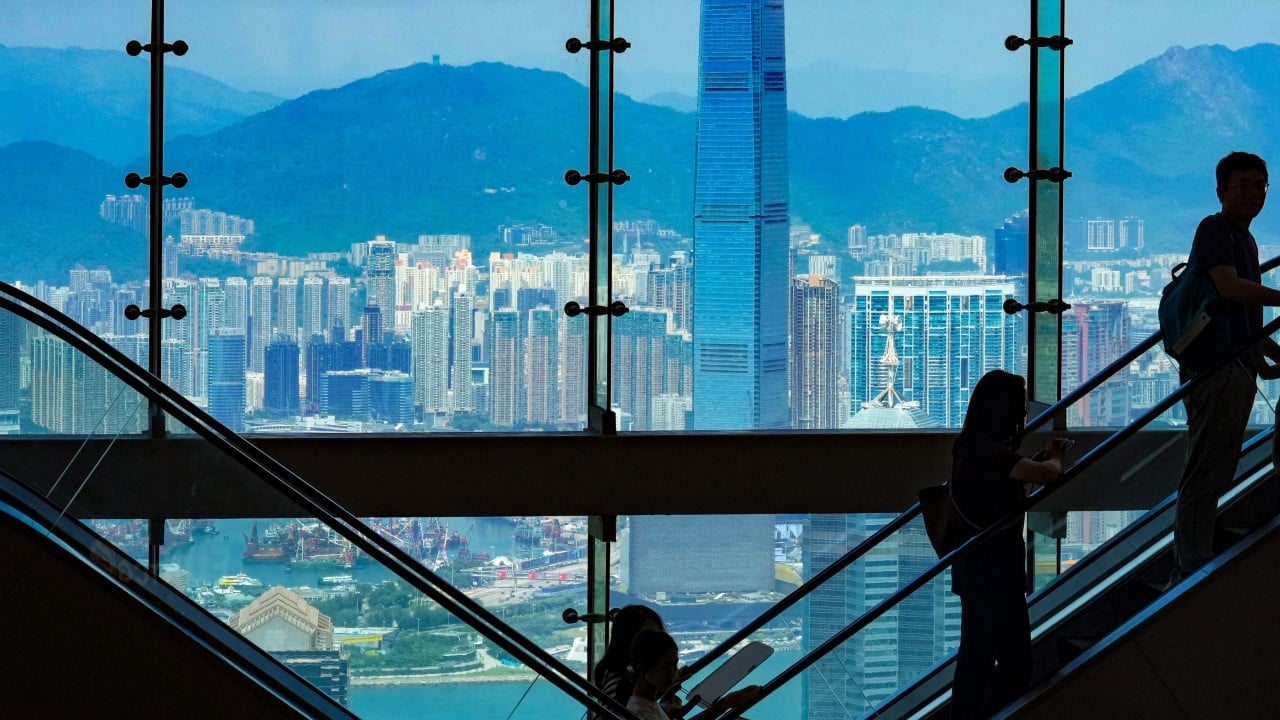
In a fast-moving development shaping the World landscape, Higher interest rates have weighed on property markets in both Hong Kong and New York, but Morgan Stanley sees greater upside potential in the Asian financial hub – particularly the office segment – in the months ahead, according to its latest report. Fresh reporting, according to dispatches from South China Morning Post (Asia), underscores emerging structural shifts that are drawing scrutiny across industry circles.
Executive Key Takeaways
- Primary Signal: Higher interest rates have weighed on property markets in both Hong Kong and New York, but Morgan Stanley sees greater upside potential in the Asian financial hub – particularly the office segment – in the months ahead, according to its latest report.
- Contextual Driver: The US investment bank highlighted the similarities between two of the world’s leading financial centres, pointing out that Hong Kong’s monetary policy moved in lockstep with the US Federal Reserve, while both cities faced limited land supply,...
- Strategic Outlook: Market and policy watchers anticipate critical regulatory and macroeconomic responses.
Higher interest rates have weighed on property markets in both Hong Kong and New York, but Morgan Stanley sees greater upside potential in the Asian financial hub – particularly the office segment – in the months ahead, according to its latest report. The US investment bank highlighted the similarities between two of the world’s leading financial centres, pointing out that Hong Kong’s monetary policy moved in lockstep with the US Federal Reserve, while both cities faced limited land supply,...
Market & Strategic Implications
Beyond immediate headlines, market participants are weighing secondary effects. The intersection of capital allocations, regulatory scrutiny, and shifting macroeconomic postures continues to elevate risk sensitivity across comparable assets and jurisdictions.
As further clarity emerges in upcoming briefings, institutional observers emphasize unit economics, policy enforcement, and counterparty exposure as primary barometers for long-term trajectory.
Comments (0)
No comments yet. Be the first to share your thoughts!
Leave a Comment