International Briefing: More Hong Kong homes sell at a loss despite signs prices have bottomed: agents
Despite signs that Hong Kong property prices could have bottomed out and begun rebounding in August, market sources said at least 100 secondary residential homes were sold at a loss in September, up from at least 81 the previous month. Hong Kong’s pr...
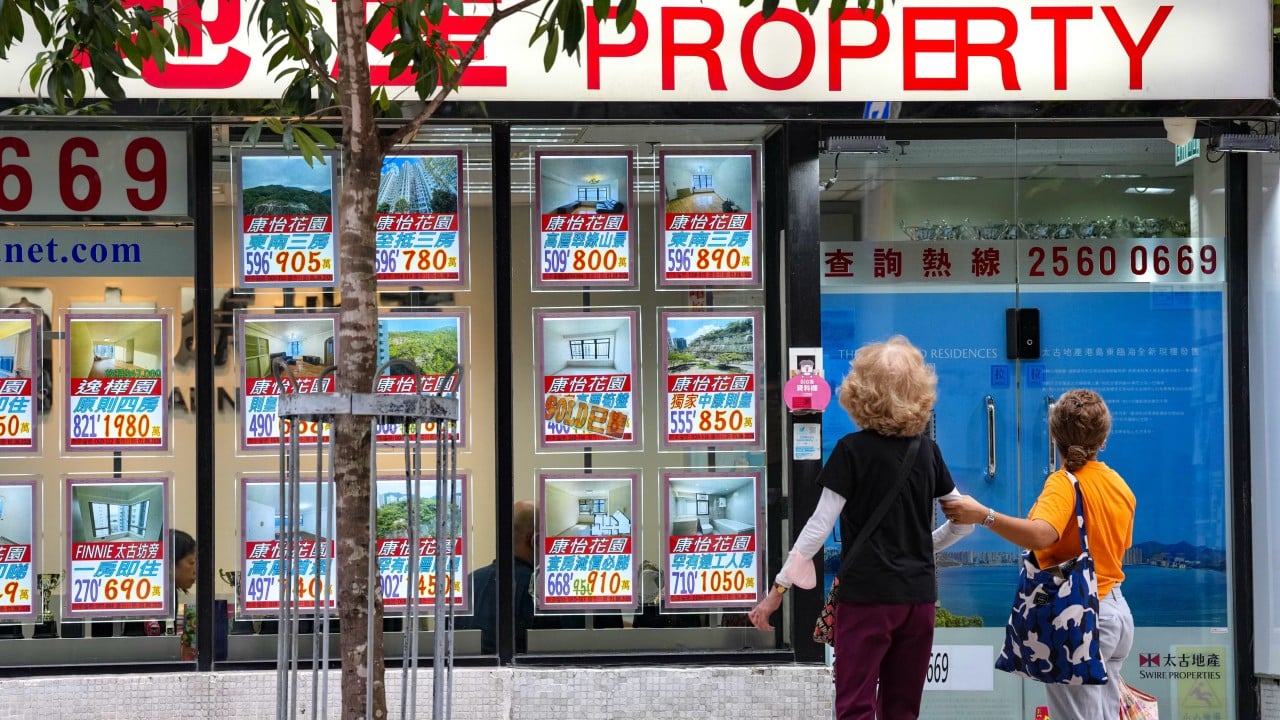
In an important development shaping the global World space, Despite signs that Hong Kong property prices could have bottomed out and begun rebounding in August, market sources said at least 100 secondary residential homes were sold at a loss in September, up from at least 81 the previous month. Recent observations, according to dispatches from South China Morning Post (Asia), point to structural shifts with notable ramifications for industry participants and analysts alike.
Executive Key Takeaways
- Primary Signal: Despite signs that Hong Kong property prices could have bottomed out and begun rebounding in August, market sources said at least 100 secondary residential homes were sold at a loss in September, up from at least 81 the previous month.
- Contextual Driver: Hong Kong’s property market dodged an immediate setback from the US Federal Reserve’s rate increase in September, and agents estimated that home prices could end the year 15 per cent higher than a year earlier.
- Strategic Outlook: The positive trend, however, did not generally apply...
Despite signs that Hong Kong property prices could have bottomed out and begun rebounding in August, market sources said at least 100 secondary residential homes were sold at a loss in September, up from at least 81 the previous month. Hong Kong’s property market dodged an immediate setback from the US Federal Reserve’s rate increase in September, and agents estimated that home prices could end the year 15 per cent higher than a year earlier. The positive trend, however, did not generally apply...
Market & Strategic Implications
Beyond immediate headlines, market participants are weighing secondary effects. The intersection of capital allocations, regulatory scrutiny, and shifting macroeconomic postures continues to elevate risk sensitivity across comparable assets and jurisdictions.
As further clarity emerges in upcoming briefings, institutional observers emphasize unit economics, policy enforcement, and counterparty exposure as primary barometers for long-term trajectory.

Comments (0)
No comments yet. Be the first to share your thoughts!
Leave a Comment