Hong Kong’s First-store Appeal Grows As More Japanese, South Korean and Thai Brands Arrive
Japanese, South Korean and Thai brands have increased their share of new entrants in Hong Kong’s retail property market by 7 percentage points to more than one-third in the first nine months of 2026, while the demand for shops from mainland Chinese b...
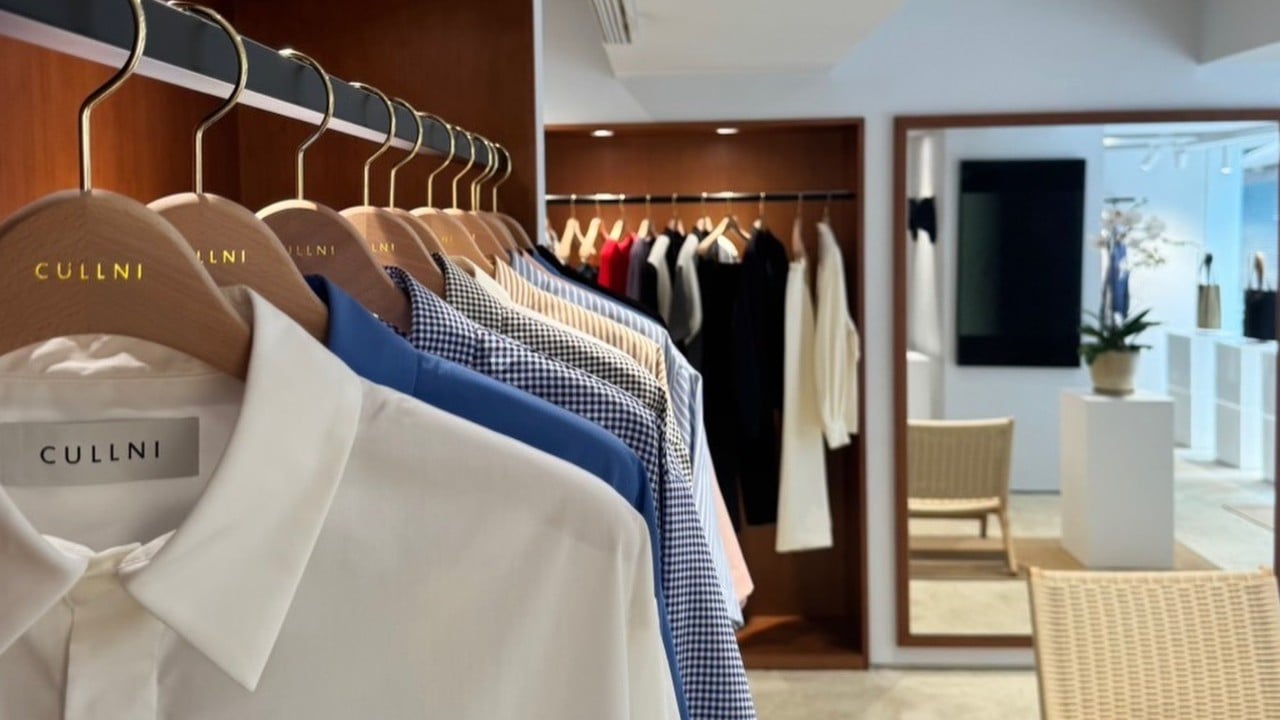
In a fast-moving development shaping the World landscape, Japanese, South Korean and Thai brands have increased their share of new entrants in Hong Kong’s retail property market by 7 percentage points to more than one-third in the first nine months of 2026, while the demand for shops from mainland Chinese brands has slipped, according to Cushman & Wakefield. Fresh reporting, according to dispatches from South China Morning Post (Asia), underscores emerging structural shifts that are drawing scrutiny across industry circles.
Executive Key Takeaways
- Primary Signal: Japanese, South Korean and Thai brands have increased their share of new entrants in Hong Kong’s retail property market by 7 percentage points to more than one-third in the first nine months of 2026, while the demand for shops from mainland Chinese brands has slipped, according to Cushman & Wakefield.
- Contextual Driver: A slew of new brands helped lift the combined share of Japanese, South Korean and Thai brands to a three-year high, according to Cushman, which said it expected the trend to continue.
- Strategic Outlook: This year,...
Japanese, South Korean and Thai brands have increased their share of new entrants in Hong Kong’s retail property market by 7 percentage points to more than one-third in the first nine months of 2026, while the demand for shops from mainland Chinese brands has slipped, according to Cushman & Wakefield. A slew of new brands helped lift the combined share of Japanese, South Korean and Thai brands to a three-year high, according to Cushman, which said it expected the trend to continue. This year,...
Market & Strategic Implications
Beyond immediate headlines, market participants are weighing secondary effects. The intersection of capital allocations, regulatory scrutiny, and shifting macroeconomic postures continues to elevate risk sensitivity across comparable assets and jurisdictions.
As further clarity emerges in upcoming briefings, institutional observers emphasize unit economics, policy enforcement, and counterparty exposure as primary barometers for long-term trajectory.
Comments (0)
No comments yet. Be the first to share your thoughts!
Leave a Comment