China’s Economy to Slow As Global Growth Stays Solid, US Think Tank Report Says
China’s economic growth is expected to slow further next year as export strength fades and weak domestic demand persists, even as the global economy remains resilient, according to a new outlook from the Peterson Institute for International Economics...
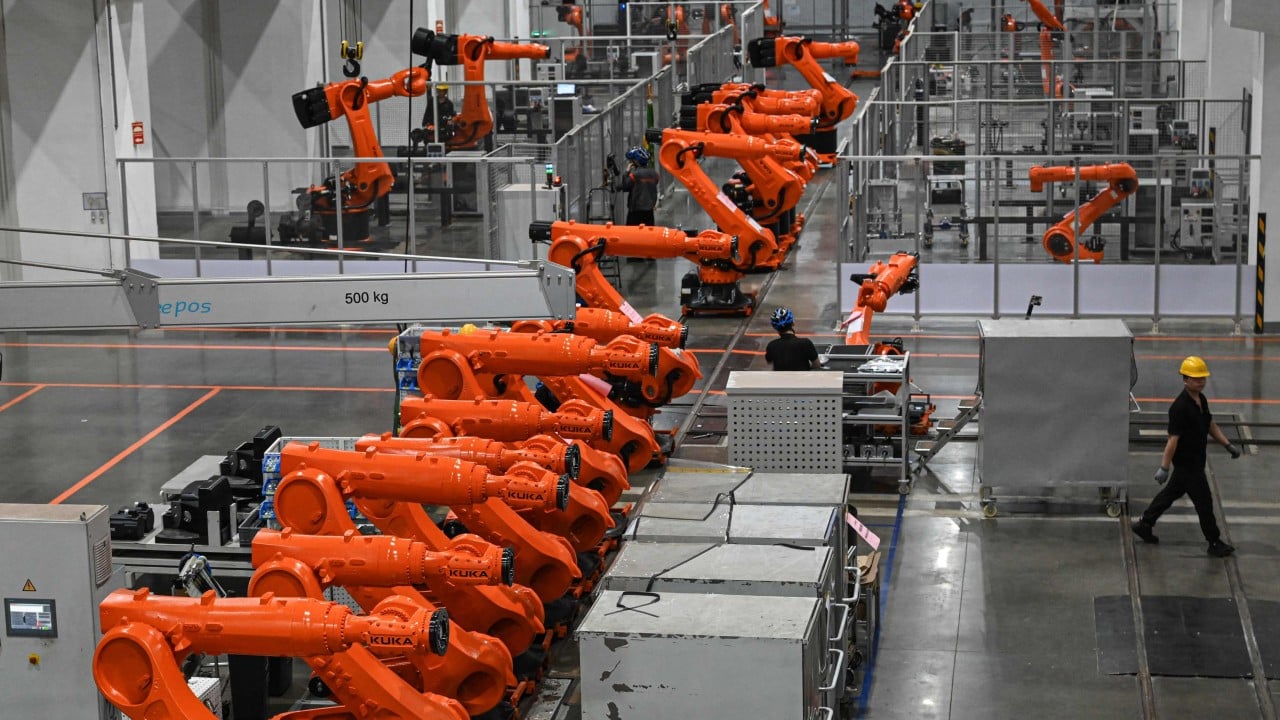
In a fast-moving development shaping the World landscape, China’s economic growth is expected to slow further next year as export strength fades and weak domestic demand persists, even as the global economy remains resilient, according to a new outlook from the Peterson Institute for International Economics (PIIE). Fresh reporting, according to dispatches from South China Morning Post (Asia), underscores emerging structural shifts that are drawing scrutiny across industry circles.
Executive Key Takeaways
- Primary Signal: China’s economic growth is expected to slow further next year as export strength fades and weak domestic demand persists, even as the global economy remains resilient, according to a new outlook from the Peterson Institute for International Economics (PIIE).
- Contextual Driver: The Washington-based think tank projects China’s GDP will grow 4.6 per cent this year and 4.3 per cent in 2027, down from 5 per cent growth in 2025, according to its semi-annual Global Economic Prospects report, released on Tuesday.
- Strategic Outlook: The...
China’s economic growth is expected to slow further next year as export strength fades and weak domestic demand persists, even as the global economy remains resilient, according to a new outlook from the Peterson Institute for International Economics (PIIE). The Washington-based think tank projects China’s GDP will grow 4.6 per cent this year and 4.3 per cent in 2027, down from 5 per cent growth in 2025, according to its semi-annual Global Economic Prospects report, released on Tuesday. The...
Market & Strategic Implications
Beyond immediate headlines, market participants are weighing secondary effects. The intersection of capital allocations, regulatory scrutiny, and shifting macroeconomic postures continues to elevate risk sensitivity across comparable assets and jurisdictions.
As further clarity emerges in upcoming briefings, institutional observers emphasize unit economics, policy enforcement, and counterparty exposure as primary barometers for long-term trajectory.
Comments (0)
No comments yet. Be the first to share your thoughts!
Leave a Comment