The Architecture of 'Friendshoring': How Mexico, Vietnam, and India Are Absorbing Hundreds of Billions in Relocated Manufacturing Capital
Global multinational supply chains are undergoing their most consequential restructuring since China’s accession to the WTO in 2001. An on-the-ground analysis of industrial park development, logistics bottlenecks, and cross-border currency dynamics driving the China+1 paradigm.
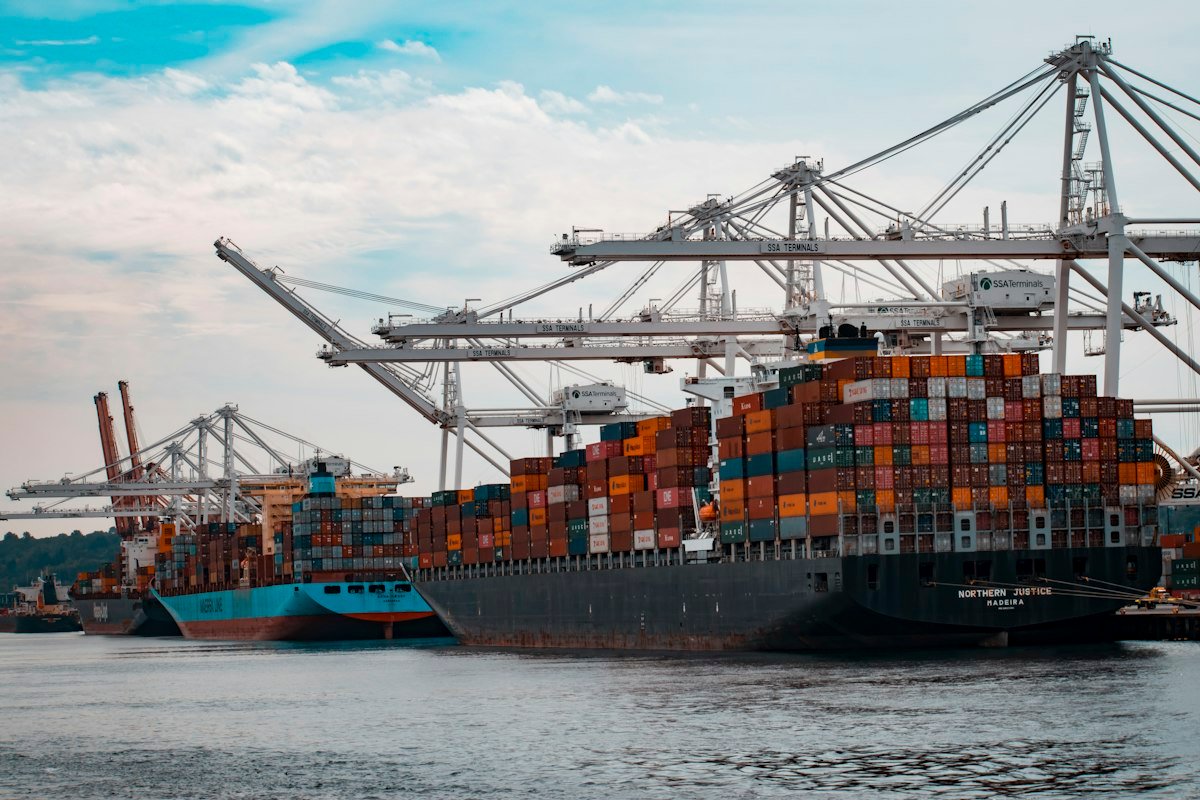
Global Trade Architecture • Supply Chain Intelligence
By Jaison M K, Senior Tech & Market Analyst at Incisor News. Mapping the multi-decade capital migration from concentrated coastal production hubs to regionalized industrial corridors across the Americas and South Asia.
• Strategic Trade Takeaways
- The End of Unilateral Sourcing: The "China+1" corporate imperative has evolved from a board-level risk discussion into hard capital deployment across Mexico, Vietnam, and India.
- Mexico\'s Nearshoring Boom: Foreign Direct Investment into northern Mexican industrial corridors has outstripped historic records, driven by zero-tariff USMCA market access.
- Infrastructure Growing Pains: Port congestion, water scarcity, and transmission grid bottlenecks in recipient countries are testing the speed and efficiency of manufacturing re-alignment.
For three decades following the conclusion of the Cold War, multinational supply chain architecture was governed by a single optimization metric: marginal cost efficiency. Manufacturing operations were concentrated wherever labor was cheapest, environmental regulations most flexible, and logistics clusters most dense. This hyper-optimized doctrine created an unprecedented era of disinflationary consumer abundance—while simultaneously concentrating the industrial capacity of the planet along China’s eastern seaboard.
That paradigm has been decisively shattered. A historic confluence of pandemic supply breakdowns, heightened geopolitical tensions across the Taiwan Strait, and escalating bilateral tariff regimes has forced corporate procurement directors to replace "just-in-time" optimization with "just-in-case" resilience.
Mexico: The Premier Nearshoring Beneficiary
No nation has captured the immediate capital flows of this restructuring more forcefully than Mexico. Leveraging the robust legal framework of the United States-Mexico-Canada Agreement (USMCA) and immediate overland rail and trucking links to the world’s largest consumer market, industrial real estate vacancy rates in northern hubs like Monterrey, Saltillo, and Tijuana have compressed below 1.5%.
Global Tier-1 automotive suppliers, medical device fabricators, and advanced electronics assemblers are investing tens of billions in turnkey industrial facilities. In 2023, Mexico officially eclipsed China as the leading exporter of goods to the United States—a historic symbolic milestone that underscores the permanence of this realignment.
"Nearshoring is not a temporary tariff evasion tactic; it is the fundamental physical re-anchoring of North American manufacturing sovereignty for the next fifty years."
Southeast Asia and India: The High-Tech Diversification Hubs
While Mexico dominates heavy manufacturing and overland freight, Southeast Asia—led by Vietnam, Malaysia, and Thailand—has emerged as the premier alternative for consumer electronics and semiconductor assembly and test (OSAT) facilities. Vietnam’s northern provinces of Bac Ninh and Thai Nguyen have become global assembly powerhouses for flagship smartphones, drawing billions in committed capex from Foxconn, Pegatron, and Luxshare.
Concurrently, India is leveraging its massive domestic market scale and government-backed Production Linked Incentive (PLI) schemes to build an integrated electronics ecosystem from the ground up. Apple’s successful scaling of iPhone assembly across Tamil Nadu and Karnataka—now accounting for approximately 14% of global iPhone production—demonstrates that India is surmounting its historic logistics and bureaucratic hurdles to achieve world-class manufacturing scale.
The Hidden Reality: The Persistent Intermediate Goods Tether
A rigorous economic examination reveals an important nuance: while finished goods are increasingly exported to Western markets from Mexico or Vietnam, the underlying intermediate components—printed circuit boards, lithium cells, precision tooling, and rare earth magnets—frequently continue to originate in mainland China.
In many sectors, Chinese industrial manufacturers have responded to Western tariffs by aggressively nearshoring themselves, investing directly in Mexican industrial parks and Vietnamese joint ventures. Western policymakers are now tightening rules of origin requirements under USMCA review provisions to ensure that relocated assembly operations deliver genuine domestic value-add rather than superficial repackaging.
Strategic Guidance for Global Executives
The re-engineering of global trade corridors is structurally inflationary: duplicating factories, securing dual-source supply chains, and training new industrial labor forces requires substantial capital outlays. Companies that execute this migration with speed and operational discipline will secure durable competitive moats; those that hesitate will find their supply chains increasingly vulnerable to geopolitical shocks and sudden tariff realignments.
Comments (0)
No comments yet. Be the first to share your thoughts!
Leave a Comment